Understand what you’re pledging, what to ask before applying and why repayment matters.
Title pawning means using your vehicle title as collateral for money you borrow. Collateral is property pledged to secure repayment, so this decision involves your vehicle, not just a document. Eligibility depends on the business’s requirements and agreement, and failure to repay can put your vehicle at risk.
Florida Title calls its service a car title pawn and serves customers in the Pensacola area through physical branches in Lillian and Seminole, Alabama. Before applying, understand what you’re pledging, ask which steps and documents apply to you, and consider whether you can meet the repayment obligation.
What Does Title Pawning Mean?
A vehicle title is the ownership document associated with your car. Using it as collateral is different from selling the vehicle: you’re taking on a repayment obligation secured by that property. Don’t assume that handing over a document limits your responsibility to the paperwork itself.
You may also hear the word lien, which means a legal claim against property that secures a debt. If that term appears in your paperwork, ask how it affects your vehicle and what must happen for the claim to be released.
Searches such as “pawn my car title” describe the general idea, but they don’t tell you the terms of an individual transaction. The Florida Title service overview introduces the business; your own requirements and obligations need to be explained before you accept an agreement.
From Application to Agreement
You can start with an online application. That starting point should not be mistaken for approval or a promise that every remaining step can be completed online. Ask what happens after submission and which steps, if any, require a branch visit.
Use these questions to understand the process before making plans:
- What happens after I submit my information? Ask how you’ll receive instructions and whether anything else is needed for review.
- How will my vehicle be evaluated? Confirm what information the business needs about it and whether you must bring it to a branch.
- What determines eligibility and the amount offered? Ask which requirements apply to your situation rather than relying on a general estimate.
- When can I review the complete terms? Read the agreement and have unclear language explained before deciding whether to accept.
The site’s overview of how the service works offers related reading. For your own application, confirm the instructions directly, including how your residence and the Alabama branch location affect the process. Serving Pensacola does not mean there is a physical office there.
Documents to Ask About
Before gathering paperwork or traveling, ask for the document list that applies to you. A general checklist found online may describe another business’s policies rather than this one’s requirements.
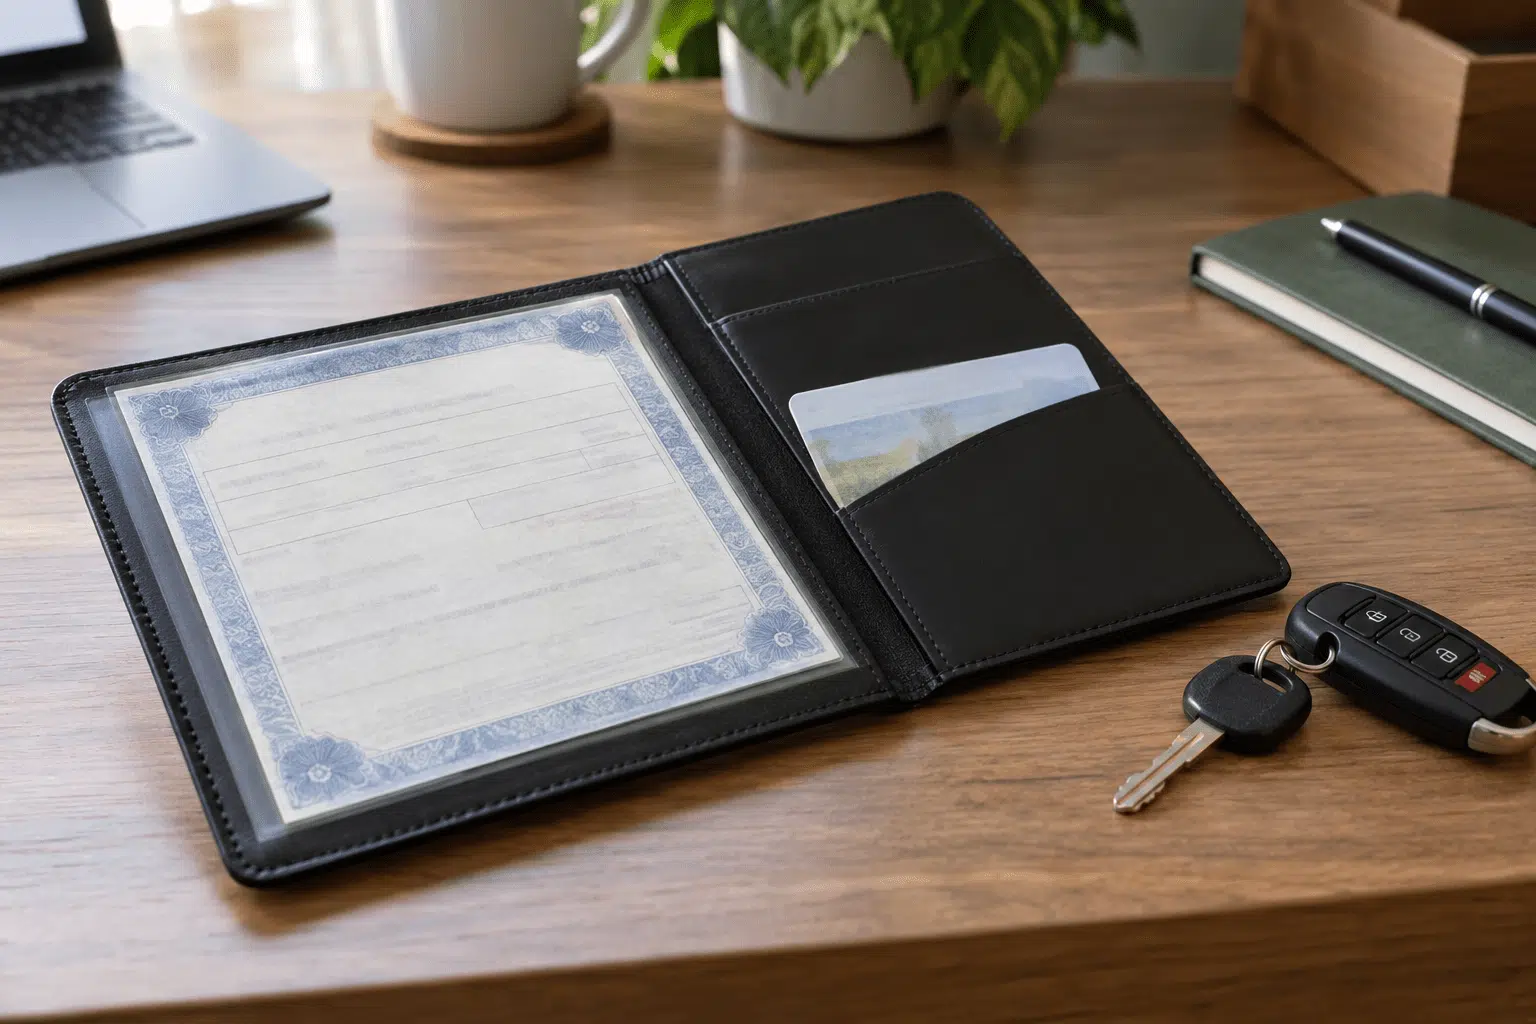
Useful questions include:
- What identification is accepted?
- What title or ownership documents do I need, and must they be originals?
- What should I do if another owner or an existing lien appears on the title?
- Do I need any income, residence, insurance or registration records?
- What can I submit online, and what must I bring in person?
These are questions to confirm, not a list of required documents. If you’re unfamiliar with the service, the first-time borrower guide is another starting point for identifying questions before you proceed.
Repayment and Vehicle Risks
Before accepting an offer, make sure you understand the total amount you’ll owe, when payment is due, how to pay and what happens if you don’t meet the agreement. Ask for an explanation of any charges or conditions you don’t understand. An amount offered to you is not, by itself, proof that it fits your budget.
Because your vehicle secures repayment, failing to pay can result in losing it. Consider what that would mean for work, errands and other responsibilities. Don’t treat repeated borrowing as a substitute for a repayment plan, or assume an extension will be available if you fall short.
If you’ve considered those responsibilities and want your situation reviewed, you can begin online. Start your application